核心要点
全国大部分地区出现零星小雨。
尽管拍卖市场恢复全周交易,全国肉牛上栏量环比下降7%。
全国羔羊与绵羊上栏量分别上涨32%和16%。
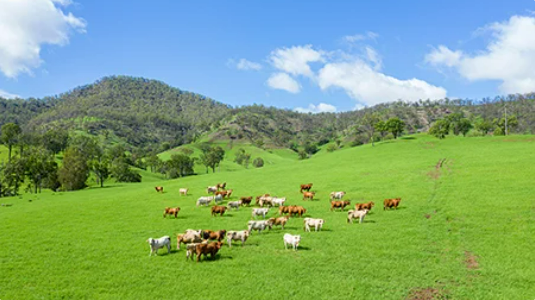
本周澳大利亚多地出现分布不均的降雨。西澳西南部、昆士兰州南部、新南威尔士州北部及新州中西部等干旱区域迎来零星降水,但仍需更多降雨才能有效缓解旱情。
肉牛市场
全国肉牛当周上栏量下降7%,至54403头。公共假期结束后拍卖市场恢复整周交易,但降雨预报促使部分养殖户选择留存牲畜暂不出售。
本周所有肉牛价格指标均出现上涨,涨幅区间从奶牛指标的0.4%至后备一岁母牛指标的11%不等。
近几周肉牛市场波动剧烈,尤其是补栏牛品类。干旱天气与不断变化的降雨预测,造成供需每周大幅震荡。
一岁后备阉牛指标本周上涨7%,达到活重548分/公斤。罗马与沃加沃加拍卖场的样本占该指标统计量的65%,市场报告显示本次上市牛只质量参差不齐。
育肥母牛指标上涨8.5%,活重报467分/公斤,本次上市量4556头,较上周减少151头。
新南威尔士州拍卖场供应量占总量63%,昆士兰州占24%。
绵羊市场
拍卖市场恢复整周交易,全国羔羊上栏量上涨32%,达到186153头,为4月以来单周最高水平。全国绵羊肉(老羊)上栏量整体增长16%,至69243头。
尽管上市量增加,价格指标依旧保持坚挺、部分小幅走高。其中美利奴羔羊指标下跌0.6%,后备补栏羔羊指标上涨2.5%。
绵羊肉指标保持稳定,胴体重价格830分/公斤,统计样本上市量46731头。
沃加沃加市场供应量占比20%,均价达到879分/公斤胴体重,存在溢价。市场报告称本次上市的重型母羊品质优异。
重型羔羊指标本周上涨1%,胴体重报价1119分/公斤,上市量22022头。
沃加沃加、本迪戈与福布斯三地市场合计占该品类总供应量的63%,所有市场反馈显示,大体重羊只订单竞争激烈。
屠宰量
统计周期:截至2026年10月9日当周
(1)牛只
屠宰量受公共假期长周末影响显著。全国肉牛屠宰量环比下降14%,至125408头。
各州肉牛屠宰量(同比):
新南威尔士州:下降10%,至25917头
昆士兰州:下降7%,至65492头
南澳大利亚州:上涨1%,至3094头
塔斯马尼亚州:上涨3%,至3883头
维多利亚州:下降5.5%,至23287头
西澳大利亚州:上涨1.5%,至3735头
(2)羊肉
屠宰量受公共假期长周末影响明显,全国羔羊屠宰量下降3.5%,至359287头。全国绵羊屠宰量下降15%,至134776头。
各州羔羊屠宰量(同比):
新南威尔士州:上涨20%,至69851头
昆士兰州:下降25%,至924头
南澳大利亚州:下降27%,至29029头
塔斯马尼亚州:上涨28.5%,至8225头
维多利亚州:上涨2%,至195739头
西澳大利亚州:上涨18%,至55519头
内容供稿:亚历克斯·弗莱,澳大利亚肉类与畜牧业协会市场信息分析师
信息截至2026年10月16日发布时准确有效
澳大利亚肉类与畜牧业协会(MLA)不对本刊物所载任何信息的准确性、完整性及时效性作出任何保证。用户使用或依赖本刊物任何内容,风险自行承担;因使用或依赖相关信息所造成的任何损失与损害,MLA概不承担任何责任。未经MLA事先书面许可,本刊物任何内容不得擅自转载、复制。凡使用MLA刊物、报告及相关信息,均须遵守MLA市场报告及信息使用条款。
消息来源:MLA
Weekly cattle and sheep market wrap
Key points
Light, scattered rainfall was recorded across large parts of the country.
Despite the return to a full week of sales, national cattle yardings fell 7% week-on-week.
National lamb and sheep yardings rose 32% and 16% respectively.
Large parts of the country received patchy rainfall this week. Dry regions across south-west WA, southern Queensland, northern NSW and central-west NSW recorded scattered rainfall, although more rain is needed to provide meaningful relief from dry conditions.
Cattle market
The national cattle yarding fell 7% over the week to 54,403 head. Despite the return to a full selling week following the public holiday period, forecast rainfall encouraged some producers to retain stock.
All cattle indicators lifted over the week, with gains ranging from 0.4% for the Dairy Cow Indicator to 11% for the Restocker Yearling Heifer Indicator.
Cattle markets have been highly volatile in recent weeks, particularly restocker categories as dry conditions and changing rainfall forecasts drive sharp weekly movements in supply and demand.
The Restocker Yearling Steer Indicator lifted 7% across the week to 548¢/kg liveweight (lwt). Roma and Wagga Wagga saleyards accounted for 65% of the indicator offering, with market reports noting a mixed quality of young cattle yarded.
The Feeder Heifer Indicator lifted 8.5% over the week to 467¢/kg lwt across an offering of 4,556 head, a drop of 151 head from the previous week.
NSW yards accounted for 63% of the total offering, while Queensland contributed 24%.
Sheep market
Returning to a full week of sales, national lamb yardings lifted 32% to 186,153 head, the highest weekly total since April. The overall mutton yarding increased 16% to 69,243 head.
Despite the larger offerings, indicators remained firm to slightly stronger, with movements ranging from a 0.6% decline in the Merino Lamb Indicator to a 2.5% lift in the Restocker Lamb Indicator.
The Mutton Indicator remained firm at 830¢/kg carcase weight (cwt) across an offering of 46,731 head.
Wagga Wagga accounted for 20% of the offering and attracted a premium averaging 879¢/kg cwt. The market report also noted an outstanding offering across heavy ewes.
The Heavy Lamb Indicator lifted 1% over the week to 1,119¢/kg cwt across an offering of 22,022 head.
Wagga Wagga, Bendigo and Forbes combined to make up 63% of the total offering across the category with all reports noting strong competition for orders across heavier weights.
Slaughter
Week ending 9 October 2026
(1)Cattle
Slaughter was heavily impacted by the public holiday long weekend. National cattle slaughter numbers decreased 14% week-on-week to 125,408 head.
State-by-state cattle slaughter (YoY):
NSW: down 10% to 25,917 head
Queensland: down 7% to 65,492 head
SA: up 1% to 3,094 head
Tasmania: up 3% to 3,883 head
Victoria: down 5.5% to 23,287 head
WA: up 1.5% to 3,735 head.
(2)Sheep
Slaughter was heavily impacted by the public holiday long weekend with national lamb slaughter decreasing 3.5% to 359,287 head. The national sheep slaughter declined 15% to 134,776 head.
State-by-state lamb slaughter (YoY):
NSW: up 20% to 69,851 head
Queensland: down 25% to 924 head
SA: down 27% to 29,029 head
Tasmania: up 28.5% to 8,225 head
Victoria: up 2% to 195,739 head
WA: up 18% to 55,519 head.
Attribute content to: Alex Fry, MLA Market Information Analyst
Information is correct at time of publication on 16 October 2026
MLA makes no representations as to the accuracy, completeness or currency of any information contained in this publication. Your use of, or reliance on, any content is entirely at your own risk and MLA accepts no liability for any losses or damages incurred by you as a result of that use or reliance. No part of this publication may be reproduced without the prior written consent of MLA. All use of MLA publications, reports and information is subject to MLA’s Market Report and Information Terms of Use.
Source:MLA

